A Conditional Approval Pending Divorce Decree Finalization Letter is a formal document issued by lenders when a mortgage application is approved contingent upon a legal end to a marriage. This ensures that financial liabilities and asset divisions are legally clarified before closing. Below are some ready to use template options to help you navigate this specific real estate requirement.
Image cover: Mortgage Conditional Approval Pending Divorce Decree: Letter Templates and Guide
Letter Samples List
- Conditional Approval Pending Divorce Decree Finalization Letter
- Conditional Approval Pending Sale of Departure Residence Letter
- Conditional Approval Pending Bankruptcy Discharge Documentation Letter
- Conditional Approval Pending Gift Fund Transfer Verification Letter
- Conditional Approval Pending Clear Property Title Resolution Letter
- Conditional Approval Pending Earnest Money Deposit Clearance Letter
- Conditional Approval Pending Certificate of Occupancy Issuance Letter
- Conditional Approval Pending Final Verification of Employment Letter
- Conditional Approval Pending Living Trust Agreement Review Letter
- Conditional Approval Pending Homeowners Insurance Binder Letter
- Conditional Approval Pending Estate Probate Completion Letter
- Conditional Approval Pending Tax Return Transcript Verification Letter
- Conditional Approval Pending Property Appraisal Condition Repair Letter
- Conditional Approval Pending Lien Subordination Agreement Finalization Letter
Conditional Approval Pending Divorce Decree Finalization Letter
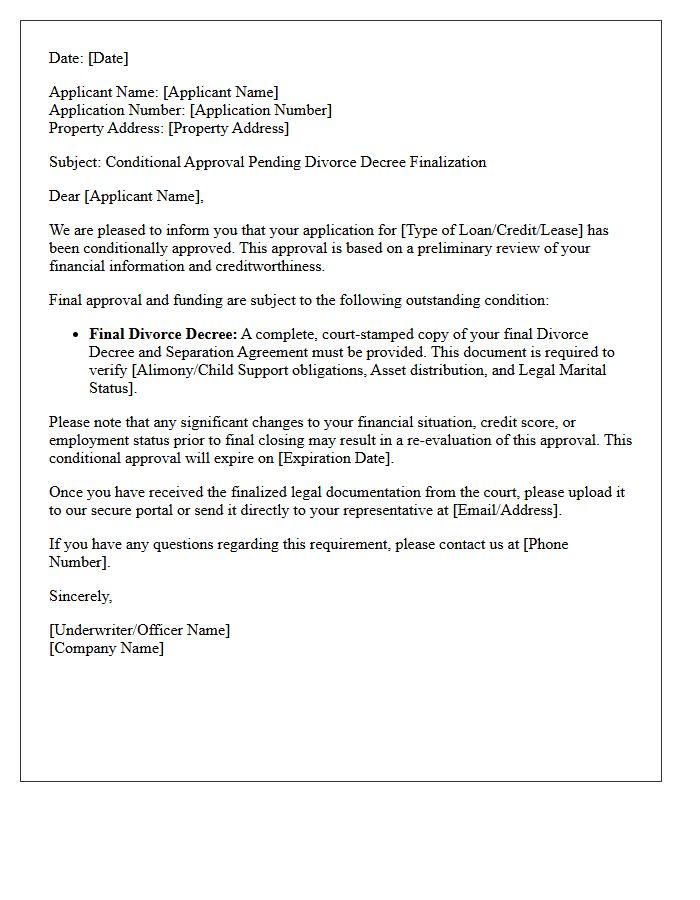
A Conditional Approval Pending Divorce Decree Finalization Letter is a lender's preliminary commitment to provide a mortgage once a legal settlement is officially recorded. It signifies that the borrower meets credit and income criteria, provided the final court order confirms specific financial obligations like alimony, child support, or property division. This document is crucial for home buyers navigating a marital dissolution, as it allows them to proceed with property searches while awaiting the formal decree required to close the loan and verify their final debt-to-income ratio.
Conditional Approval Pending Sale of Departure Residence Letter
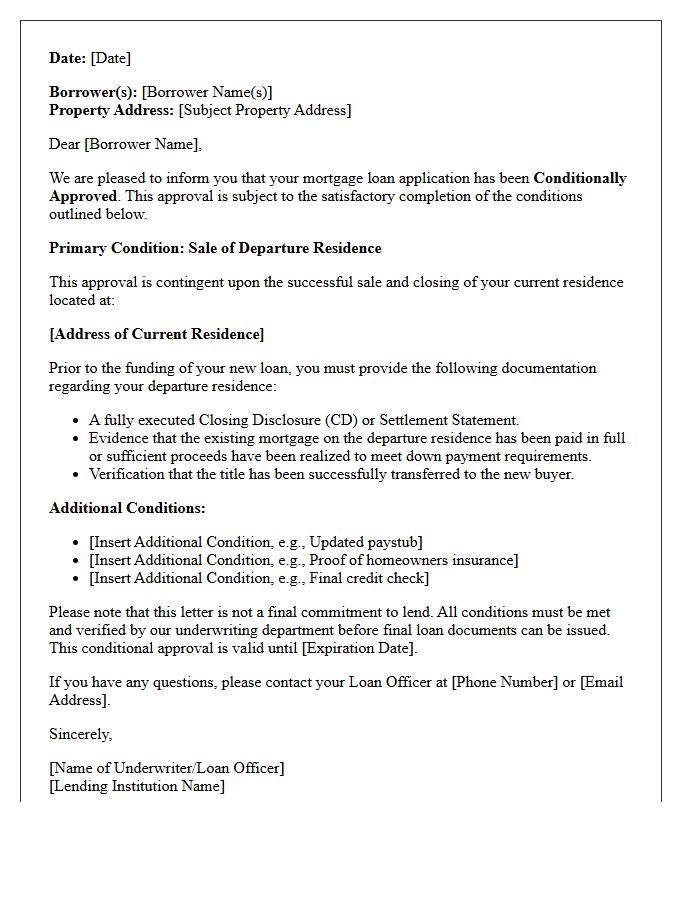
A Conditional Approval Pending Sale of Departure Residence letter is a formal document issued by a lender to homebuyers. It confirms that a new mortgage is approved, provided the borrower successfully sells their current home first. This contingency protects the lender by ensuring the borrower maintains a manageable debt-to-income ratio without carrying two mortgages simultaneously. For sellers, receiving an offer with this letter indicates the buyer is creditworthy but must finalize their own property disposition before closing. It is a critical milestone in managing complex real estate contingencies and financing timelines.
Conditional Approval Pending Bankruptcy Discharge Documentation Letter
A Conditional Approval Pending Bankruptcy Discharge Documentation Letter is a lender's commitment to provide financing once official discharge papers are provided. This letter signifies that a borrower meets all underwriting criteria except for the formal legal conclusion of their bankruptcy case. It is crucial for securing housing or loans during the waiting period, proving that financial stability is restored. Applicants must ensure their court-ordered discharge is finalized and documented to satisfy the condition and move from preliminary approval to a fully funded loan agreement.
Conditional Approval Pending Gift Fund Transfer Verification Letter
A Conditional Approval Pending Gift Fund Transfer Verification Letter is a formal notice from a lender indicating that a mortgage is approved, provided the borrower proves the source and receipt of gifted down payment funds. To satisfy this condition, you must submit a signed gift letter and documented bank statements showing the money moving from the donor's account to yours. Ensuring a clear paper trail is essential to verify that the funds are not undisclosed loans, allowing the final underwriting process to conclude successfully.
Conditional Approval Pending Clear Property Title Resolution Letter
A Conditional Approval Pending Clear Property Title Resolution Letter is a formal notice indicating that a mortgage is approved, provided specific ownership encumbrances are resolved. This document highlights issues like unpaid liens, judgments, or conflicting claims discovered during a title search. Borrowers must clear these legal clouds to ensure the lender obtains a first-priority security interest. Securing a clean title is the final hurdle before loan funding, as it protects the buyer's investment and the lender's collateral from future legal disputes or financial claims.
Conditional Approval Pending Earnest Money Deposit Clearance Letter
A Conditional Approval Pending Earnest Money Deposit Clearance Letter confirms a lender has vetted your finances but requires verified proof that your deposit has cleared your bank account. This document ensures the buyer has skin in the game before final loan commitment. To avoid delays, provide a certified bank statement or a cleared check image showing the funds leaving your account. Once the escrow agent confirms receipt and the lender verifies the source of funds, this specific condition is satisfied, moving the mortgage closer to the final clear to close status.
Conditional Approval Pending Certificate of Occupancy Issuance Letter
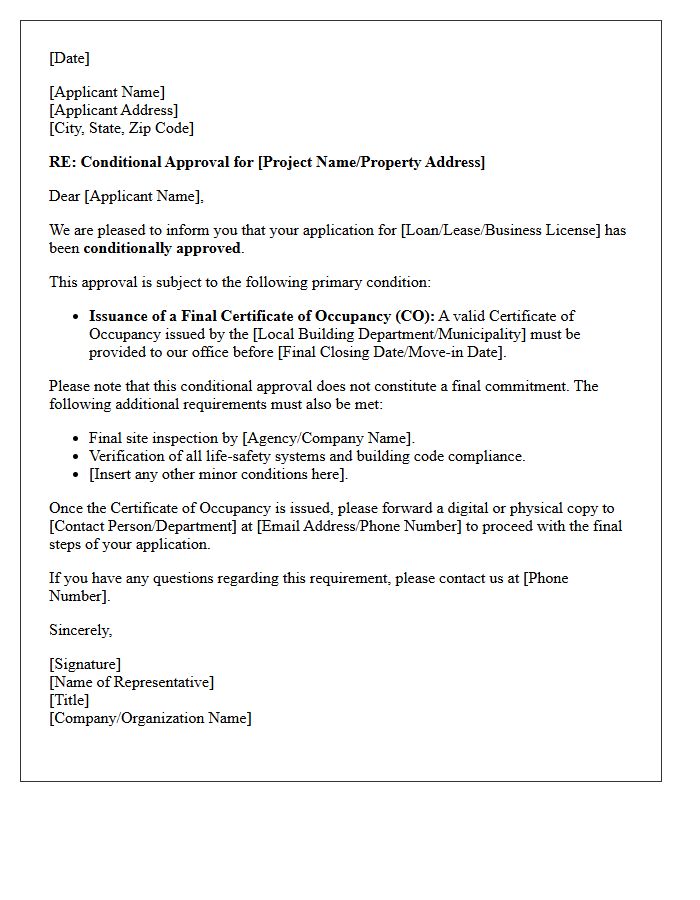
A Conditional Approval Pending Certificate of Occupancy Issuance Letter is a formal document from a lender or building department indicating that a loan or project is approved, provided a final Certificate of Occupancy (CO) is obtained. This letter is crucial for new constructions or renovations, confirming the structure meets all safety codes and zoning laws. It acts as a bridge to final funding or occupancy, ensuring the property is legally habitable before the transaction concludes. Receiving this letter means only the final inspection stands between you and official property possession.
Conditional Approval Pending Final Verification of Employment Letter
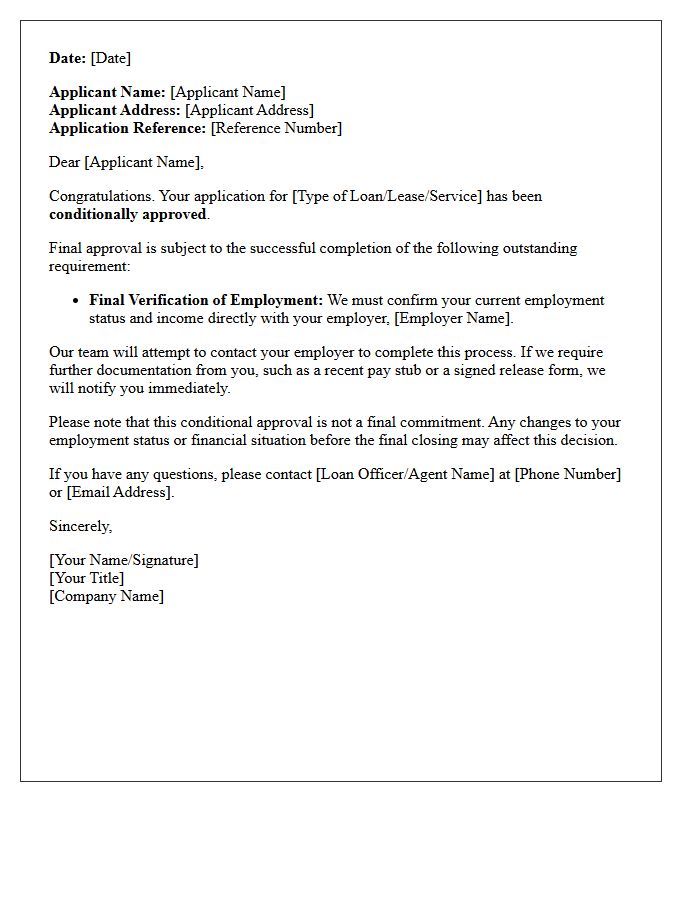
A conditional approval indicates your mortgage is approved provided you meet specific requirements before closing. The most critical step is the final verification of employment. Lenders perform this check shortly before funding to ensure your income status remains unchanged. If you lose your job or change positions, the loan can be denied. To ensure a smooth process, keep your employer's contact information updated and avoid career changes until the verification letter is confirmed and the loan is funded. Stability is essential for securing your home financing.
Conditional Approval Pending Living Trust Agreement Review Letter
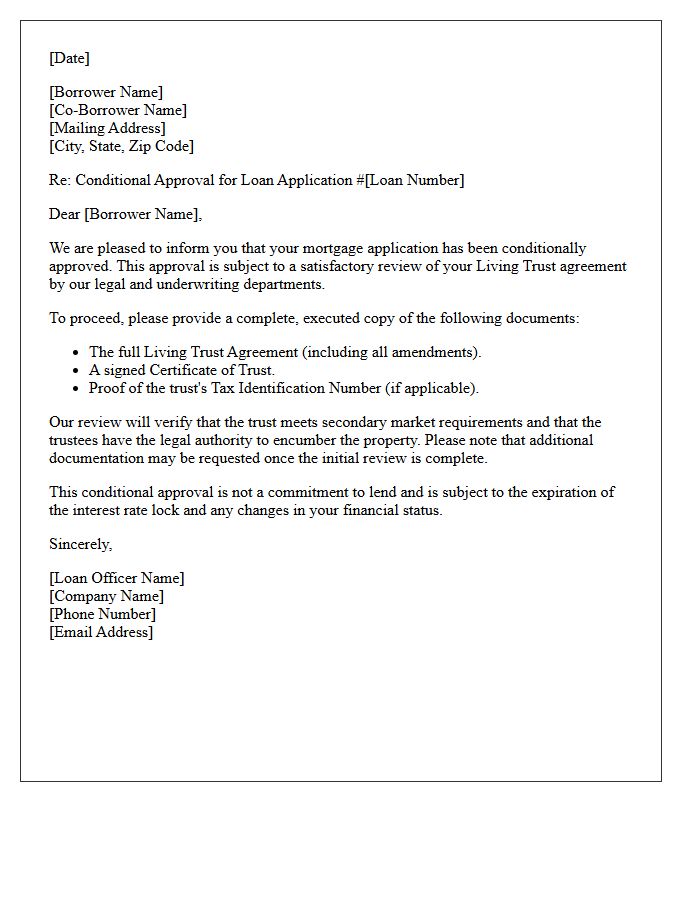
A Conditional Approval Pending Living Trust Agreement Review Letter indicates your mortgage is approved, provided the lender verifies your trust documents. Underwriters must ensure the Living Trust complies with secondary market guidelines to protect their security interest. To prevent delays, promptly submit the complete, signed Trust Agreement or a formal Certification of Trust. This review confirms the entity can legally hold title and that the trustees possess the authority to execute loan documents, ensuring a smooth transition to final approval and closing.
Conditional Approval Pending Homeowners Insurance Binder Letter
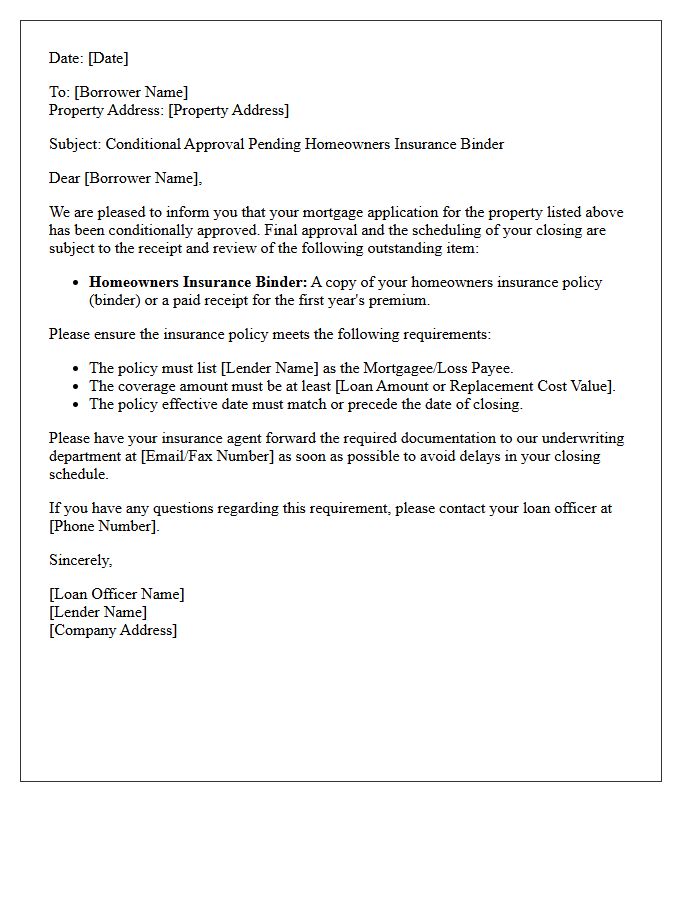
A Conditional Approval Pending Homeowners Insurance Binder Letter is a critical document issued by lenders during the mortgage process. It signifies that your loan is approved, provided you supply a valid insurance binder. This letter confirms that the property will be protected against hazards before closing. To avoid delays, ensure the binder lists the correct mortgagee clause and meets the lender's specific coverage limits. Once the binder is submitted and verified, the condition is cleared, allowing your home purchase to proceed toward the final closing disclosure and funding stage.
Conditional Approval Pending Estate Probate Completion Letter
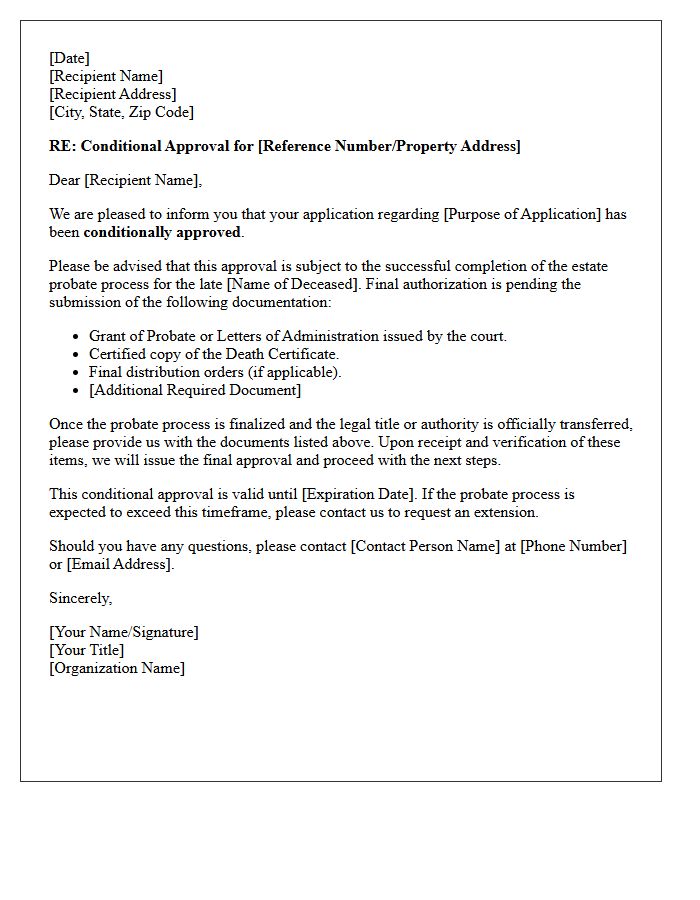
A Conditional Approval Pending Estate Probate Completion Letter is a formal document issued by lenders during real estate transactions involving a deceased owner. It states that a mortgage is approved, provided the probate process is legally finalized. This letter ensures the seller has the legal authority to transfer the clear title to the buyer. It is a critical milestone that protects all parties by confirming financial readiness while waiting for the court to validate the executor's rights to sell the property. Understanding this contingency is essential for managing closing timelines effectively.
Conditional Approval Pending Tax Return Transcript Verification Letter
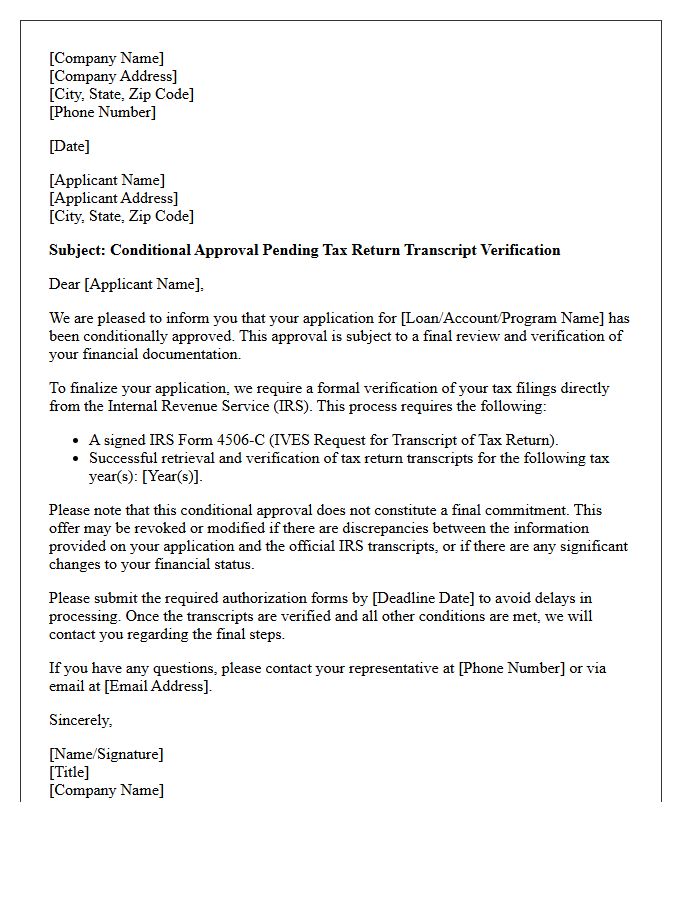
A Conditional Approval Pending Tax Return Transcript Verification Letter indicates your loan is pre-approved, provided the lender confirms your reported income. The IRS must provide official transcripts to verify that your tax filings match your application data. This verification step is crucial for final mortgage authorization. To avoid delays, ensure your IRS Form 4506-C is accurate and your tax returns are processed. This letter is not a final commitment but a significant milestone confirming your financial eligibility subject to document authentication.
Conditional Approval Pending Property Appraisal Condition Repair Letter
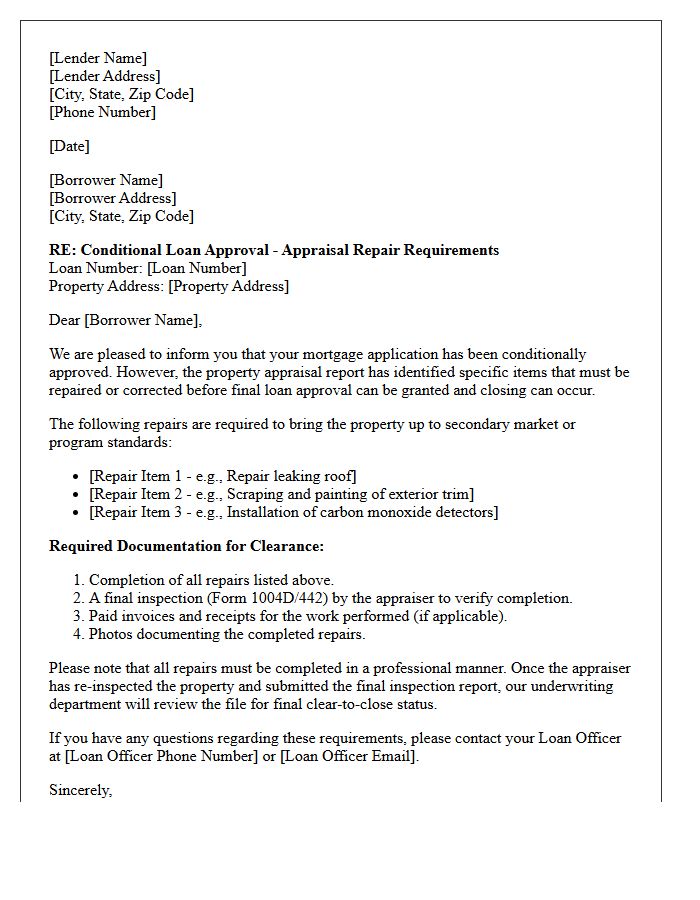
A Conditional Approval indicates a lender will fund your loan once specific requirements are met. When a Property Appraisal Condition Repair Letter is issued, it means the appraiser identified safety, structural, or habitability issues that must be fixed before closing. These mandatory repairs ensure the home meets minimum property standards for the loan program. To clear this condition, the seller typically completes the work, followed by a final inspection to confirm the property value and condition are secured. Addressing these repairs promptly is essential for final loan underwriting approval.
Conditional Approval Pending Lien Subordination Agreement Finalization Letter
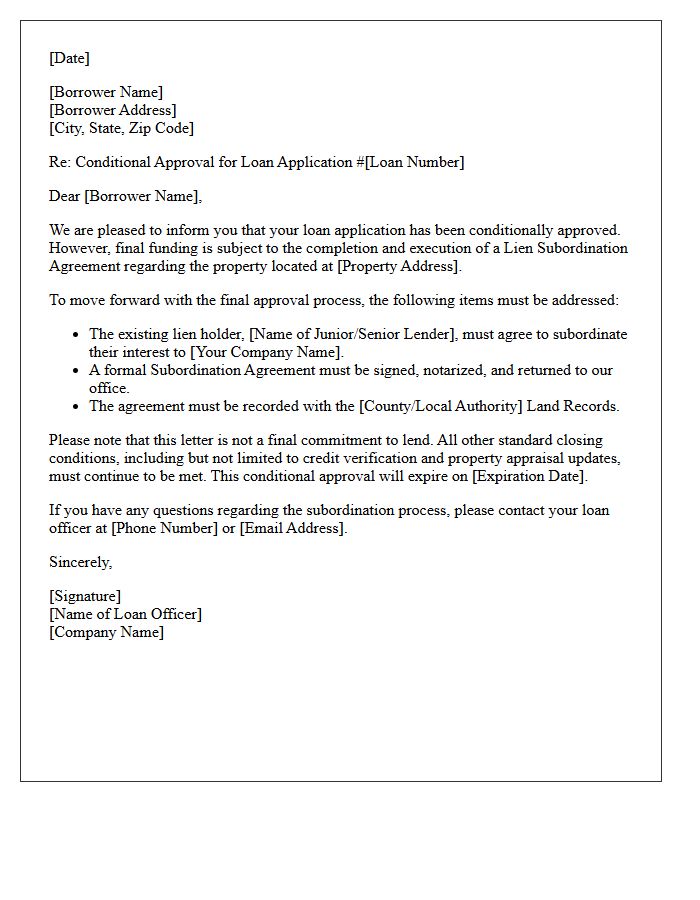
A Conditional Approval Letter indicates a mortgage lender is willing to finance your loan, provided specific requirements are met. The most critical contingency here is the Lien Subordination Agreement. This legal process occurs when a secondary lender agrees to remain in a lower priority position behind the primary mortgage. Your loan cannot reach final closing until this agreement is signed and recorded. Ensuring all parties coordinate quickly on this document is essential to prevent funding delays and secure your property financing.
What is a conditional approval letter pending a divorce decree?
It is a formal notification from a lender stating that your loan application is approved, provided you submit a finalized, court-stamped divorce decree to verify alimony, child support, or asset distribution.
Why do lenders require a final divorce decree before closing?
Lenders require the final decree to accurately calculate your debt-to-income (DTI) ratio, confirming whether you owe or receive support payments and ensuring there are no outstanding legal claims on the property.
Can I get a mortgage while my divorce is still pending?
Yes, you can receive a conditional approval; however, most lenders will not allow you to sign the final closing documents until the divorce is legally finalized and the decree is recorded.
What specific information from the divorce decree does the underwriter need?
The underwriter looks for the judge's signature, the division of marital debts, the specific amount of maintenance payments, and verification of which party is responsible for any existing mortgage or real estate liens.
How long do I have to provide the final divorce decree after receiving conditional approval?
Typically, the decree must be provided before your interest rate lock expires or within 30 to 60 days, depending on the lender's specific commitment period and the anticipated court date.

Comments