A comfort letter provides critical assurance to underwriters during municipal securities offerings by verifying financial data and auditing consistency. These documents help mitigate legal risks and ensure compliance with regulatory standards during the due diligence process. Understanding the specific requirements for local government debt issuance is essential for legal and financial professionals. Below are some ready to use templates.
Image cover: Industry Guide: Standard Comfort Letter Templates for Municipal Securities Offerings
Letter Samples List
- Standard Engagement Letter for Municipal Securities Offering Comfort Letters
- Draft Municipal Securities Offering Comfort Letter
- Final Municipal Securities Offering Comfort Letter
- Bring-Down Municipal Securities Offering Comfort Letter
- Underwriter Representation Letter for Municipal Securities Comfort Letters
- Management Representation Letter for Municipal Securities Comfort Letters
- Auditor Independence Letter for Municipal Securities Offering Comfort Letters
- Agreed-Upon Procedures Letter for Municipal Securities Offering Comfort Letters
- Subsequent Events Inquiry Letter for Municipal Securities Offering Comfort Letters
- Negative Assurance Letter for Municipal Securities Offering Comfort Letters
- Auditor Consent Letter for Municipal Securities Offering Comfort Letters
- Legal Counsel Opinion Letter for Municipal Securities Offering Comfort Letters
Standard Engagement Letter for Municipal Securities Offering Comfort Letters
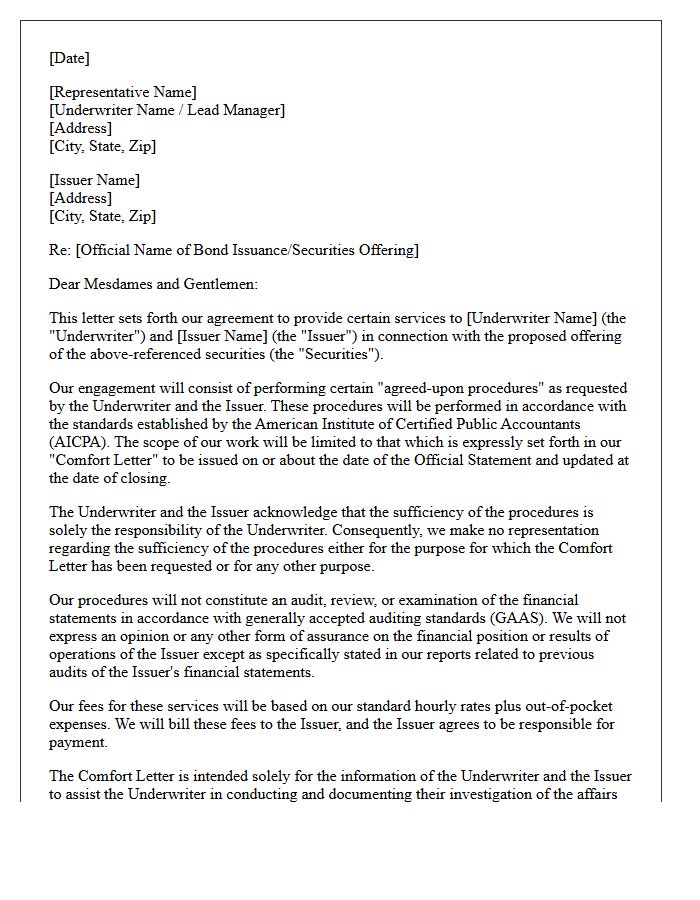
A Standard Engagement Letter establishes the contractual framework between an issuer and accountants for providing comfort letters. It defines the specific scope of procedures, liability limitations, and professional standards like AS 6101. This document is essential in a municipal securities offering to ensure all parties understand the due diligence requirements. By clearly outlining responsibilities, it mitigates legal risks and ensures the financial data presented to underwriters is verified according to agreed-upon terms, facilitating a transparent and compliant issuance process for public entities.
Draft Municipal Securities Offering Comfort Letter
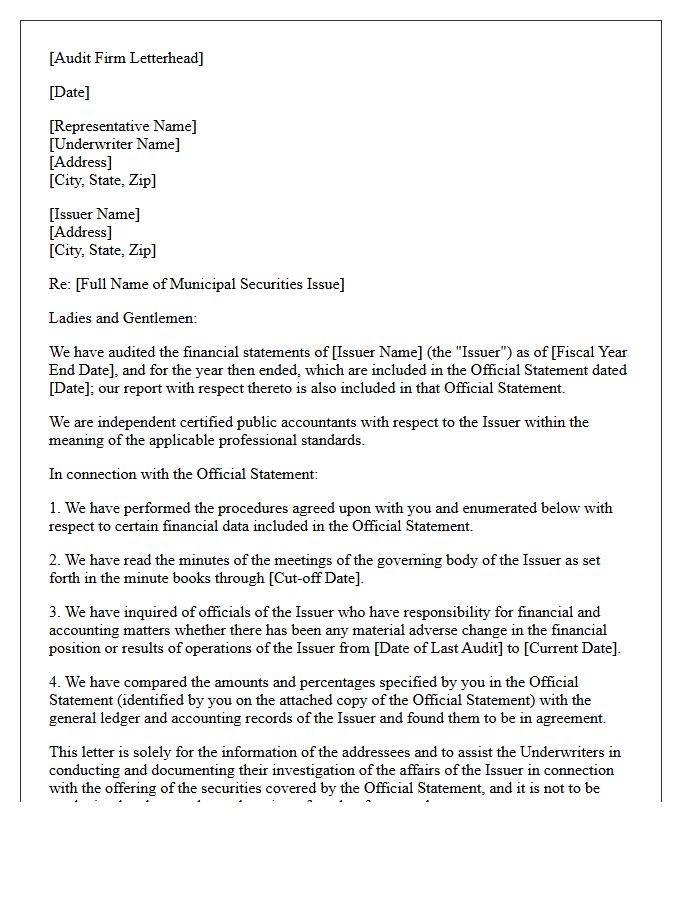
A draft municipal securities offering comfort letter is a critical due diligence document issued by independent auditors to underwriters. It provides negative assurance that financial data in the official statement complies with accounting standards and has undergone specific verification procedures. This process mitigates legal risks by establishing a "reasonable investigation" defense under securities laws. Key components include financial consistency, verification of subsequent changes, and adherence to agreed-upon procedures, ensuring the accuracy of non-audited numeric disclosures before the final bond sale and closing.
Final Municipal Securities Offering Comfort Letter
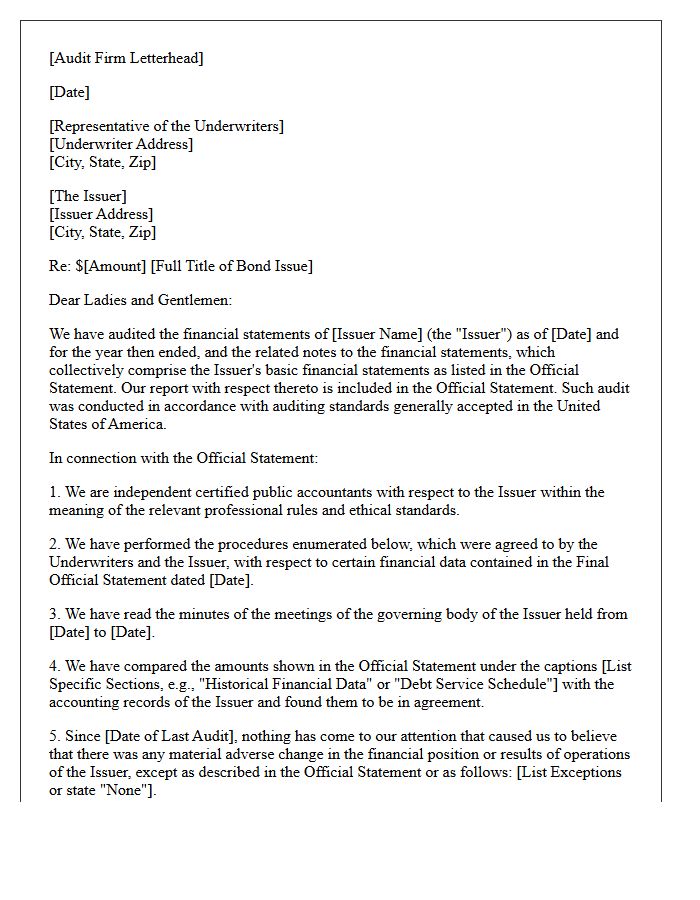
A Final Municipal Securities Offering Comfort Letter is a legal assurance issued by independent auditors to underwriters. It confirms that specific financial data within the official statement aligns with audited records. This document mitigates risk by verifying that no material changes occurred between the initial audit and the closing date. By performing "agreed-upon procedures," accountants provide negative assurance, helping underwriters establish a due diligence defense under securities laws and ensuring the integrity of the information provided to municipal bond investors.
Bring-Down Municipal Securities Offering Comfort Letter
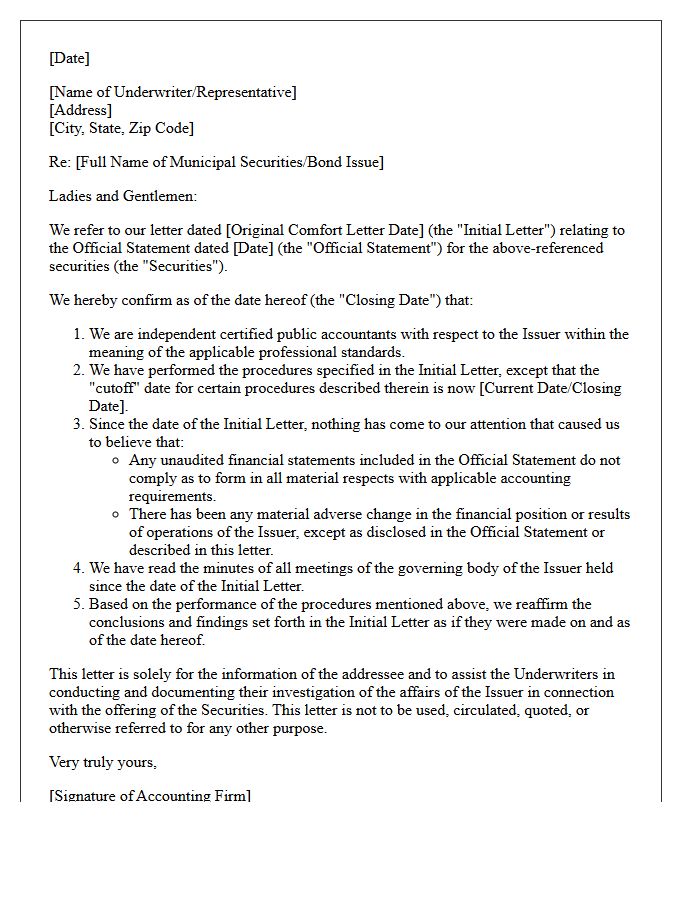
A Bring-Down Comfort Letter is a critical document issued by independent auditors to underwriters at the closing of a municipal securities offering. Its primary purpose is to reconfirm that no material adverse changes have occurred in the issuer's financial position since the date of the initial comfort letter. This process ensures due diligence requirements are met under federal securities laws. By verifying ongoing financial stability through the closing date, the letter mitigates risk for underwriters and maintains transparency for investors regarding the issuer's current fiscal health and accountability.
Underwriter Representation Letter for Municipal Securities Comfort Letters
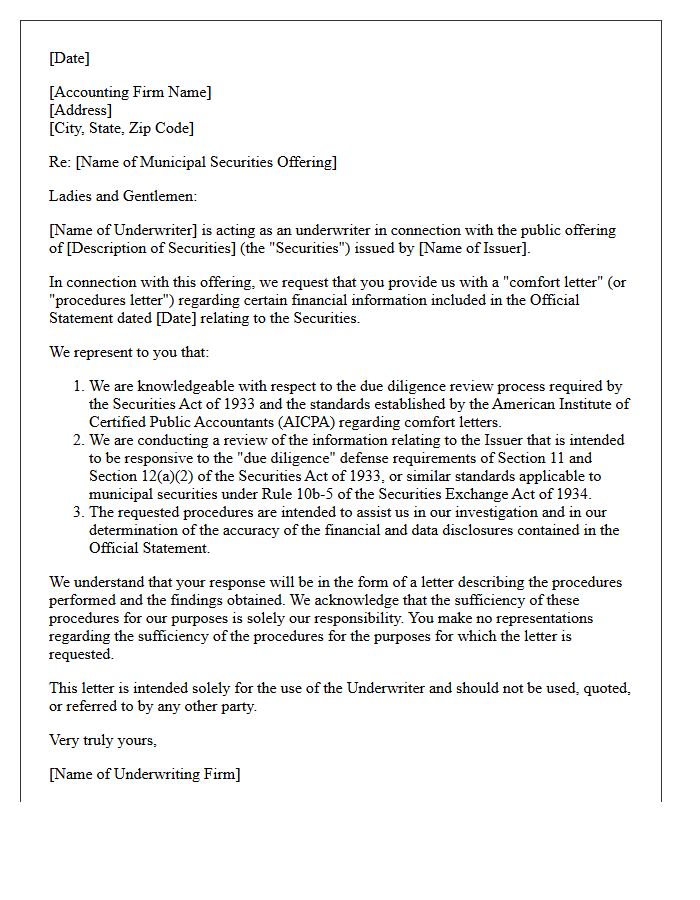
An Underwriter Representation Letter is a critical document provided to auditors to facilitate the issuance of a comfort letter. It confirms that the underwriter has performed a due diligence process consistent with the standards of the Securities Act. By signing this letter, the underwriter establishes their "due diligence defense," allowing auditors to provide negative assurance on financial data within municipal offering documents. This formal certification ensures all parties meet regulatory expectations while managing liability and ensuring the accuracy of financial disclosures in the municipal securities market.
Management Representation Letter for Municipal Securities Comfort Letters
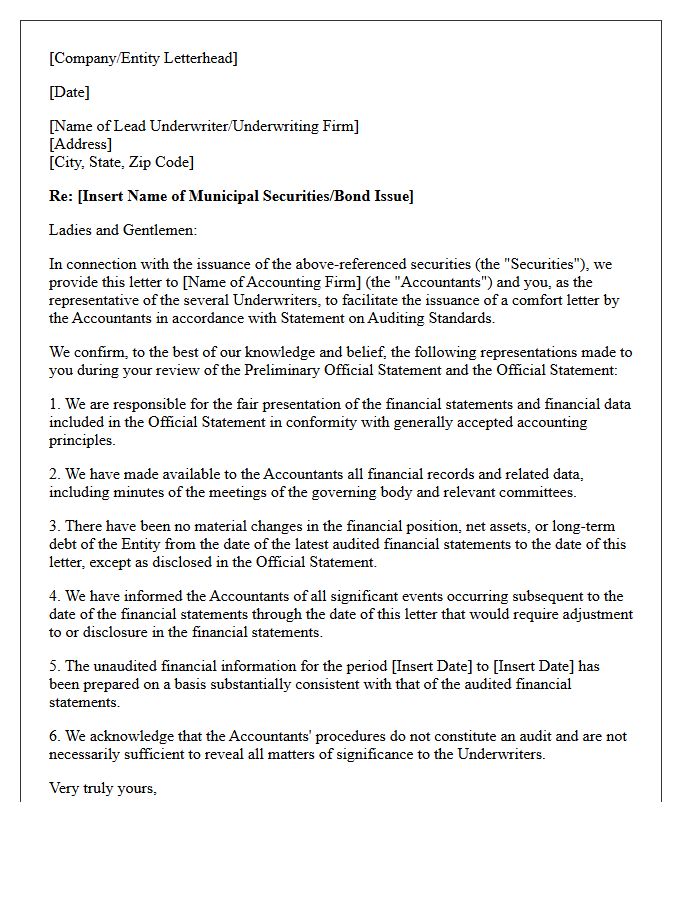
A Management Representation Letter is a critical prerequisite for auditors issuing a comfort letter in municipal securities offerings. It establishes the legal accountability of municipal officials regarding the accuracy of financial data and the absence of material changes since the last audit. This document bridges the information gap for underwriters, ensuring that management confirms internal controls and fiscal disclosures remain reliable. By formally validating interim financial information, the letter protects stakeholders and facilitates the due diligence process necessary for public debt issuance and regulatory compliance.
Auditor Independence Letter for Municipal Securities Offering Comfort Letters
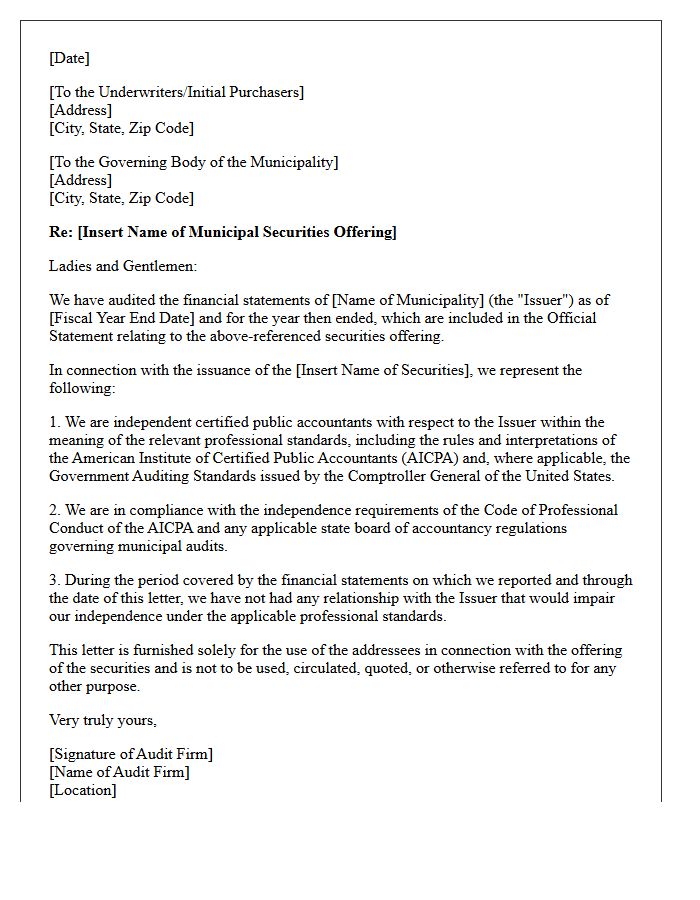
An Auditor Independence Letter is a critical document in municipal securities offerings that confirms the accountant's objectivity under AICPA and SEC standards. It serves as a prerequisite for issuing comfort letters, ensuring that the financial data provided to underwriters is verified by an unbiased third party. This letter mitigates regulatory risk by validating that no financial or personal conflicts exist between the auditor and the issuer. For investors and underwriters, it establishes trust in the integrity of the financial disclosures, which is essential for maintaining compliance and market transparency during the bond issuance process.
Agreed-Upon Procedures Letter for Municipal Securities Offering Comfort Letters
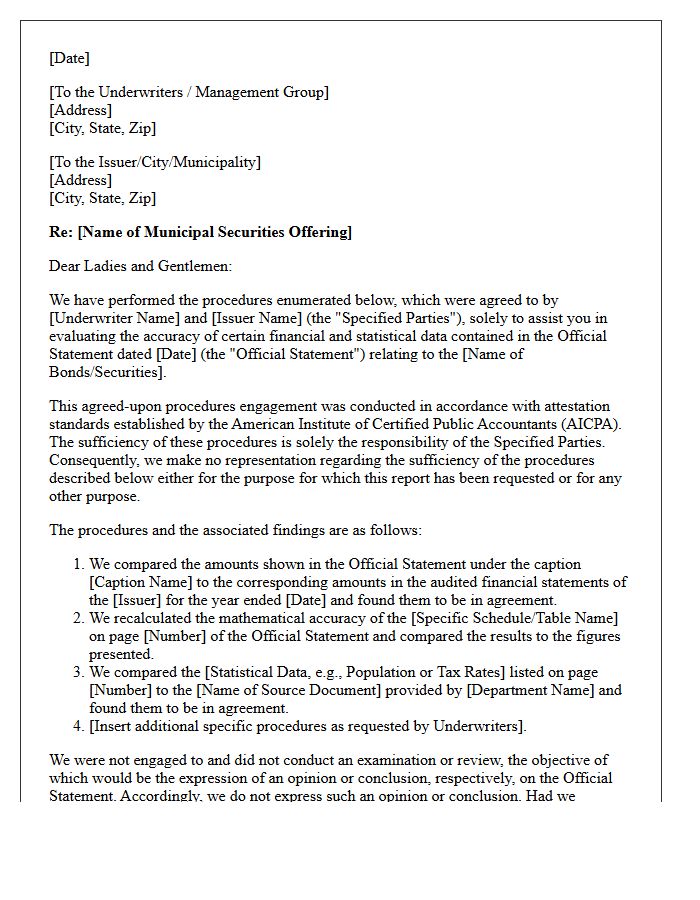
An Agreed-Upon Procedures letter, often part of comfort letter services, provides specific verification for municipal securities offerings. Under AICPA standards, accountants perform defined tasks requested by underwriters to validate financial data within official statements. Unlike a full audit, the practitioner expresses no opinion or formal assurance. Instead, they report factual findings regarding numerical accuracy and consistency. This process is crucial for due diligence, helping underwriters mitigate risk by ensuring the reliability of supplemental financial disclosures before bond issuance.
Subsequent Events Inquiry Letter for Municipal Securities Offering Comfort Letters
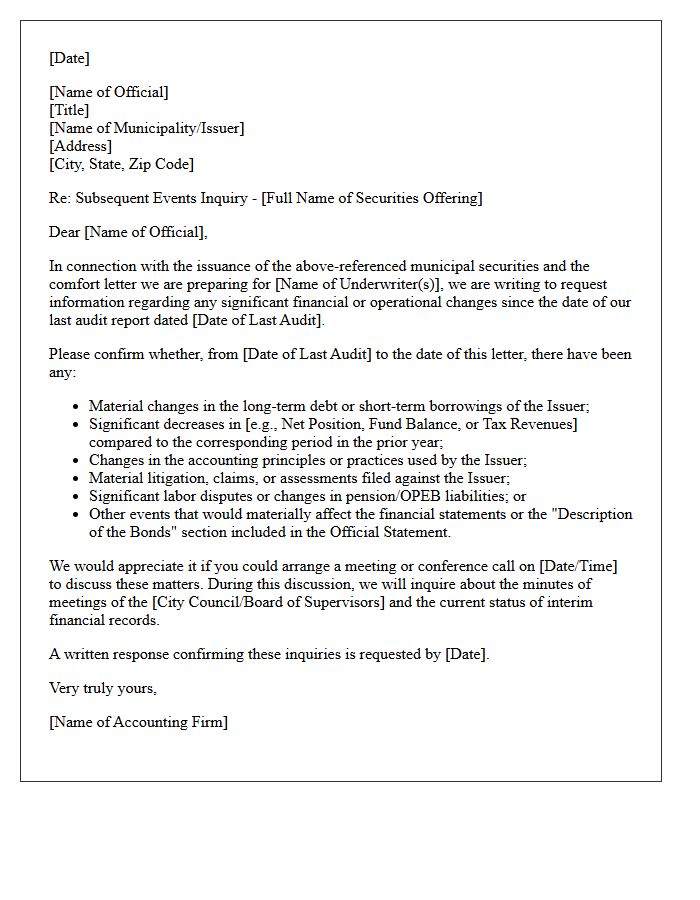
A subsequent events inquiry letter is a critical component of the due diligence process for municipal securities. It facilitates the issuance of a comfort letter by verifying that no material financial changes or adverse developments occurred between the audit date and the offering's closing. Auditors use this inquiry to confirm the accuracy of official statements, ensuring investor protection through updated disclosure. This procedure mitigates legal risks for underwriters by documenting a thorough investigation into the issuer's current fiscal health and operational status before final security delivery.
Negative Assurance Letter for Municipal Securities Offering Comfort Letters
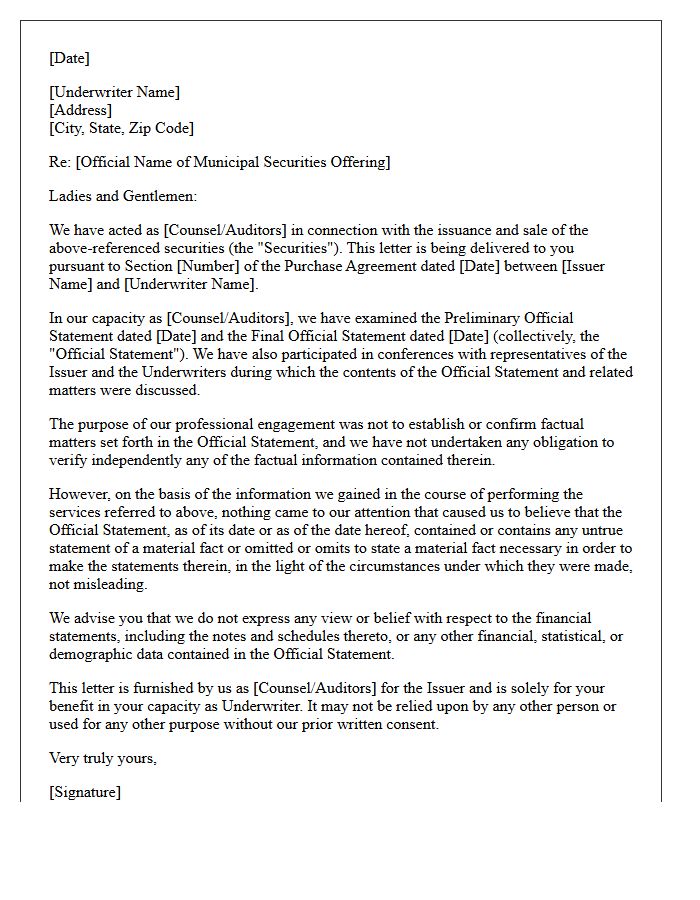
A Negative Assurance Letter is a critical component of comfort letters provided by accountants during municipal securities offerings. It confirms that, based on specific procedures, no material misstatements or omissions were identified in the financial data. While not a full audit, it provides underwriter due diligence protection by ensuring financial consistency. This statement bridges the gap between audited statements and the closing date, offering limited assurance that the offering document remains accurate. It is essential for managing liability and enhancing investor confidence in the disclosure process.
Auditor Consent Letter for Municipal Securities Offering Comfort Letters
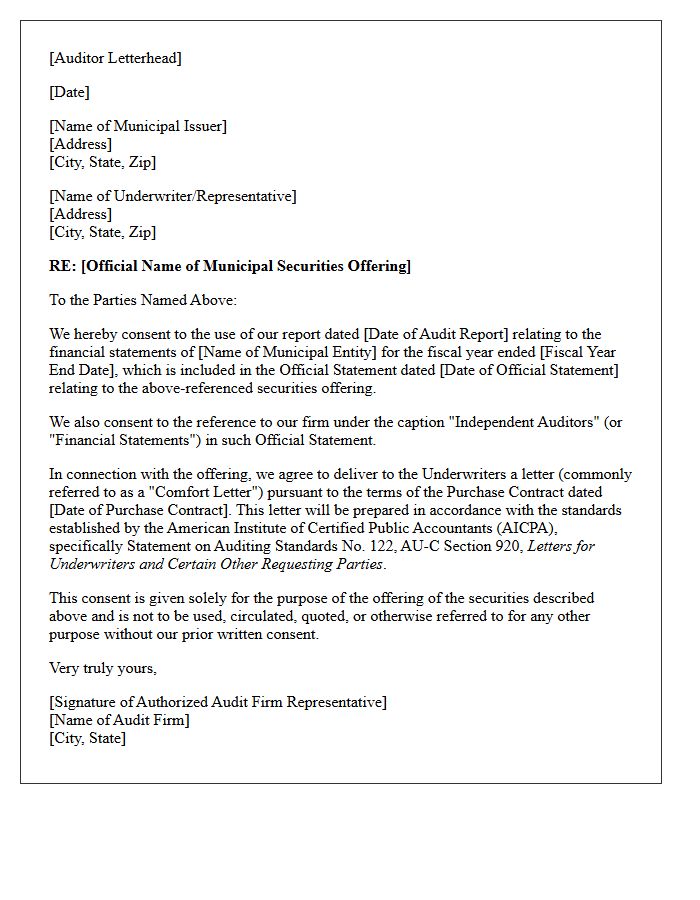
An Auditor Consent Letter is a critical legal document where independent accountants grant formal permission to include their audit reports in municipal securities offering statements. This letter ensures compliance with regulatory requirements and establishes the auditor's accountability for financial data. It is often a prerequisite for issuing Comfort Letters, which provide underwriters with negative assurance regarding unaudited financial changes. Understanding the specific scope and timing of these consents is essential for maintaining due diligence standards and protecting stakeholders during the debt issuance process in the municipal market.
Legal Counsel Opinion Letter for Municipal Securities Offering Comfort Letters
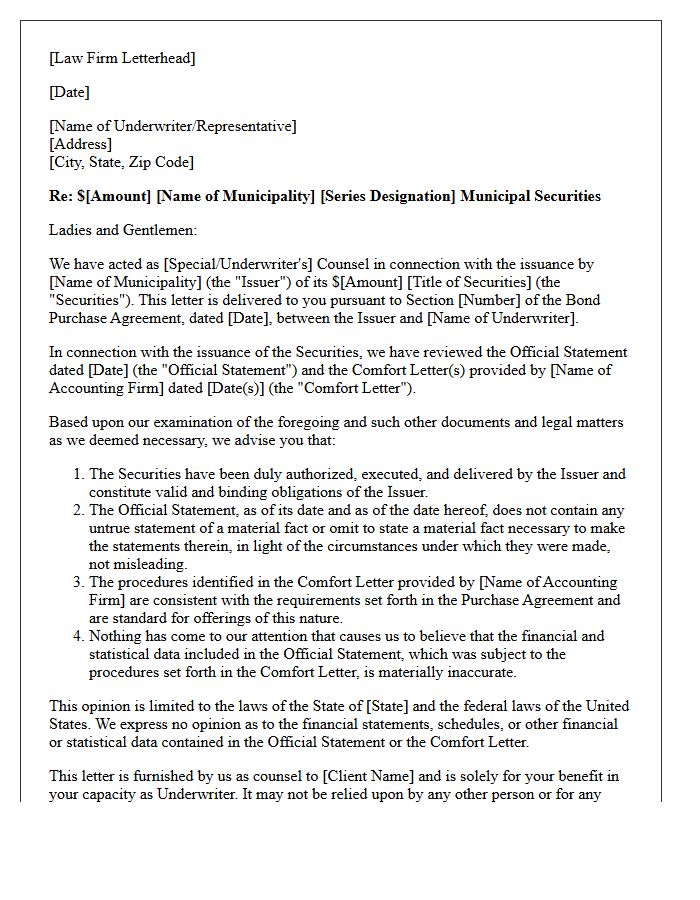
A Legal Counsel Opinion Letter is a critical document in a municipal securities offering that provides legal assurance regarding the validity and tax-exempt status of the bonds. Often accompanied by comfort letters from auditors, these documents mitigate risks for underwriters by verifying compliance with federal and state laws. They ensure that all material facts are accurately disclosed, protecting investors from potential legal discrepancies. This formal validation is essential for maintaining market integrity and establishing the legal framework necessary for a successful debt issuance within the municipal finance sector.
What is a comfort letter in a municipal securities offering?
A comfort letter is a document issued by an independent auditor to underwriters that provides negative assurance regarding the accuracy of financial data in an official statement that has not been audited. It serves as a key component of the underwriters' due diligence process to ensure compliance with federal anti-fraud provisions.
What is the primary purpose of a comfort letter for municipal underwriters?
The primary purpose is to assist underwriters in establishing a "due diligence" defense under federal securities laws. It verifies that since the date of the last audited financial statements, there have been no material adverse changes in the issuer's financial position and that specific numerical data in the offering document matches the issuer's accounting records.
What standards govern the issuance of comfort letters for municipal bonds?
Comfort letters are typically prepared in accordance with the American Institute of Certified Public Accountants (AICPA) Professional Standards, specifically AU-C Section 920. This standard dictates the scope of procedures an auditor can perform and the specific language required to provide negative assurance to requesting parties.
What is the difference between "positive assurance" and "negative assurance" in a comfort letter?
Positive assurance is provided in the audit report regarding the fairness of historical financial statements. In contrast, a comfort letter provides negative assurance, where the auditor states that nothing came to their attention during specific procedures-such as reviewing interim financial statements or reading board minutes-that indicated a material change or inconsistency.
What specific financial information is typically "ticked and tied" in a municipal comfort letter?
Auditors "tick and tie" specific tables, percentages, and financial figures found in the Official Statement (OS) to the issuer's general ledger, budget documents, or internal financial reports. This process ensures that the quantitative data presented to investors is consistent with the underlying accounting records of the municipality.

Comments