A Conditional Approval Pending Satisfactory Appraisal letter is a formal notice issued by lenders indicating a loan is approved, provided the property valuation meets the required amount. This crucial document ensures the collateral secures the requested financing before final funding. Understanding this requirement helps borrowers navigate the closing process smoothly. Below are some ready to use template.
Image cover: Template and Sample: Conditional Approval Subject to Satisfactory Appraisal Letter
Letter Samples List
- Conditional Mortgage Approval Pending Satisfactory Appraisal Letter
- Notice of Conditional Loan Approval Subject to Appraisal Letter
- Preliminary Mortgage Commitment Pending Property Appraisal Letter
- Tentative Home Loan Approval Pending Satisfactory Appraisal Letter
- Conditional Financing Approval Subject to Real Estate Appraisal Letter
- Underwriting Conditional Approval Pending Home Appraisal Letter
- Lender Notice of Conditional Approval Pending Satisfactory Appraisal Letter
- Residential Mortgage Conditional Approval Pending Appraisal Letter
- Pre-Funding Conditional Approval Subject to Property Appraisal Letter
- Home Purchase Conditional Approval Pending Satisfactory Appraisal Letter
- Conditional Loan Commitment Pending Satisfactory Property Appraisal Letter
- Approved Pending Satisfactory Real Estate Appraisal Letter
Conditional Mortgage Approval Pending Satisfactory Appraisal Letter
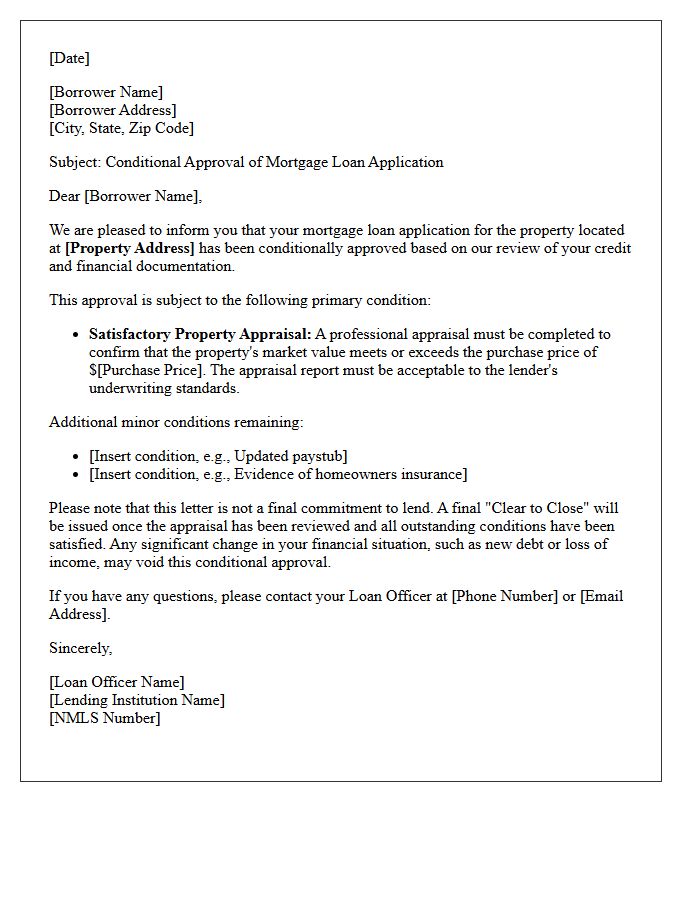
A conditional mortgage approval pending a satisfactory appraisal letter means the lender has verified your financial profile but requires a professional valuation of the property. The most critical factor is the appraisal report, which must confirm the home's market value matches or exceeds the purchase price. If the valuation comes in low, the lender may reduce the loan amount, requiring you to negotiate the price, pay the difference, or cancel the contract. This document is a vital bridge between initial pre-approval and the final commitment to fund your home loan.
Notice of Conditional Loan Approval Subject to Appraisal Letter
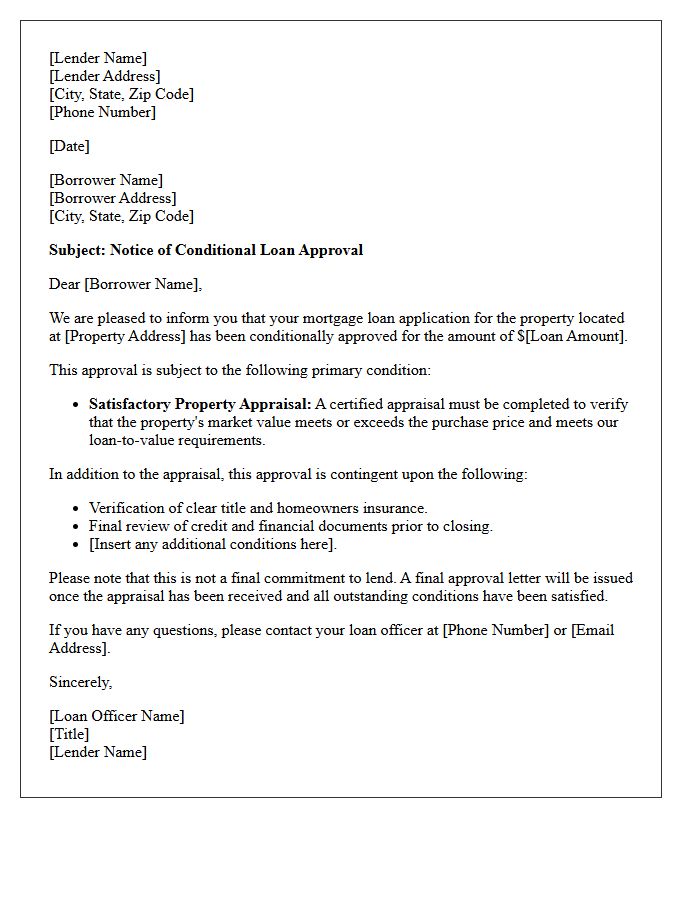
A Notice of Conditional Loan Approval Subject to Appraisal is a critical document indicating that a lender is willing to finance your home purchase, provided the property's market value meets or exceeds the offer price. This conditional commitment hinges on a professional appraisal report to protect the lender's investment. If the appraisal comes in low, the loan amount may be reduced, requiring renegotiation or a higher down payment. Receiving this letter means your financial creditworthiness is approved, but the final funding remains contingent upon the collateral valuation being verified.
Preliminary Mortgage Commitment Pending Property Appraisal Letter
A preliminary mortgage commitment pending property appraisal letter signifies that a lender has verified your financial eligibility but final approval depends on the home's value. This document confirms your creditworthiness and income are sufficient, yet remains conditional. The property appraisal is the critical final step to ensure the collateral covers the loan amount. Sellers prioritize this letter because it proves you are a qualified buyer, though the deal is not legally binding until the appraisal confirms the purchase price aligns with the market value of the asset.
Tentative Home Loan Approval Pending Satisfactory Appraisal Letter
A Tentative Home Loan Approval Pending Satisfactory Appraisal Letter indicates your mortgage is conditionally approved, provided the property's market value meets or exceeds the purchase price. This crucial valuation process protects the lender's investment and determines your final loan-to-value ratio. If the appraisal comes in lower than expected, you may need to negotiate a price reduction, increase your down payment, or dispute the findings to secure final funding. Receiving this letter is a significant milestone, confirming your creditworthiness while awaiting professional confirmation of the home's worth.
Conditional Financing Approval Subject to Real Estate Appraisal Letter
A Conditional Financing Approval indicates a lender is willing to fund your mortgage, provided specific requirements are met. The most critical contingency is the Real Estate Appraisal Letter, which confirms the property's market value. If the appraisal comes in lower than the purchase price, the lender may reduce the loan amount, requiring the buyer to cover the valuation gap out of pocket. This letter ensures the home serves as sufficient collateral, making it a vital step in securing final loan commitment and successfully closing the deal.
Underwriting Conditional Approval Pending Home Appraisal Letter
An underwriting conditional approval pending home appraisal letter indicates that a lender is willing to finance your mortgage, provided the property's market value matches the purchase price. This document confirms your creditworthiness and income are verified, but the final loan commitment is contingent upon a professional valuation. If the appraisal comes in low, it may affect your loan-to-value ratio, potentially requiring a larger down payment or price renegotiation. Securing this letter is a critical milestone, signaling that you are nearing the final clear-to-close status in the homebuying process.
Lender Notice of Conditional Approval Pending Satisfactory Appraisal Letter
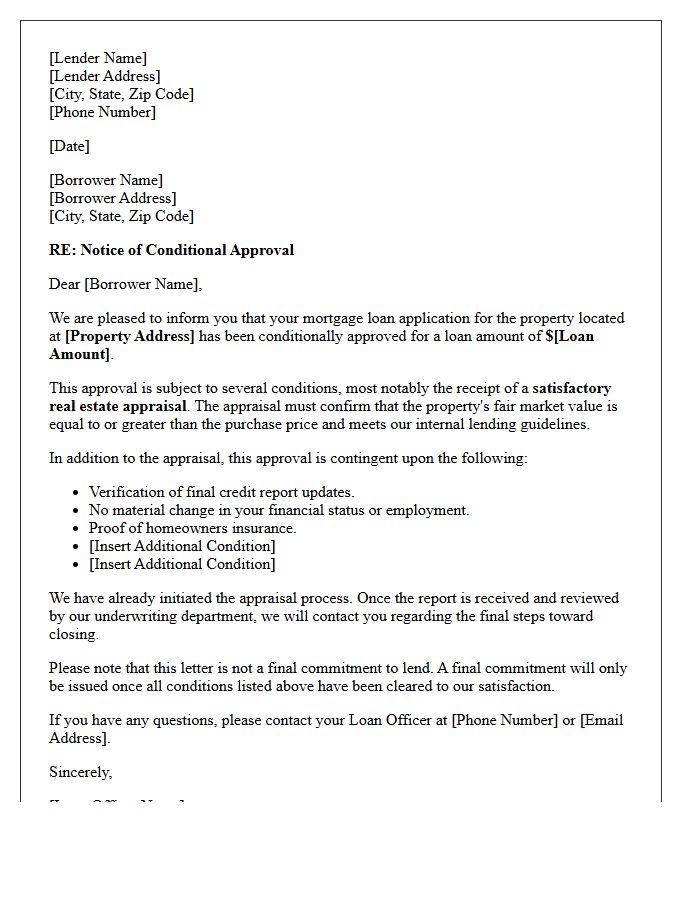
A lender's notice of conditional approval indicates that your mortgage application is pre-approved, provided the property's value meets specific requirements. The most critical factor is the satisfactory appraisal, which confirms the home's worth supports the loan amount. This letter notifies the borrower that final funding depends on a professional valuation report. If the appraisal comes in lower than the purchase price, the loan-to-value ratio may be affected, requiring a larger down payment or a price renegotiation. Always review the specific conditions listed to ensure a smooth closing process.
Residential Mortgage Conditional Approval Pending Appraisal Letter
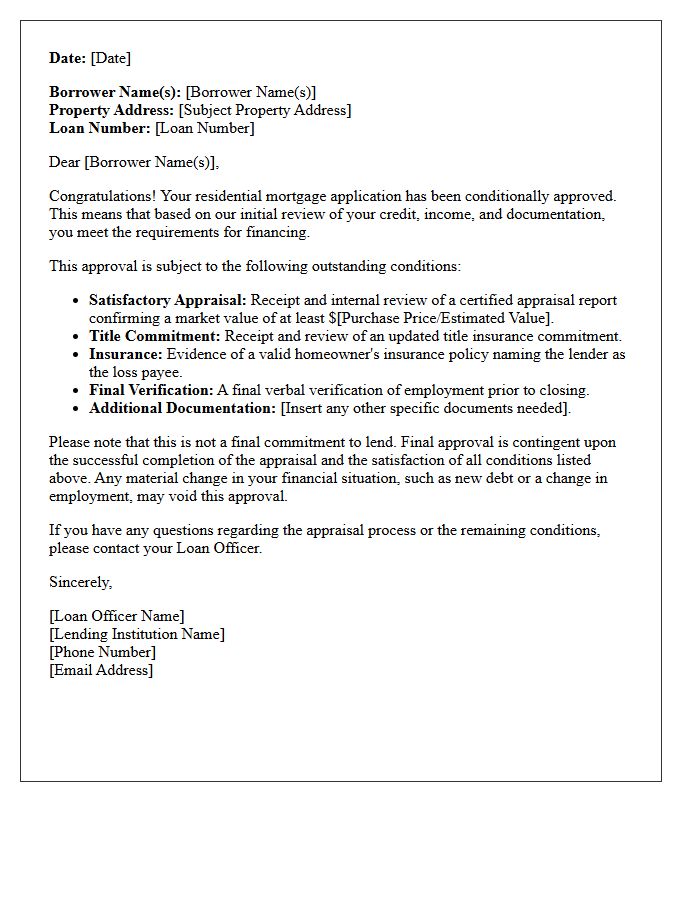
A residential mortgage conditional approval pending appraisal letter signifies that a lender is willing to finance your home, provided the property's market value meets or exceeds the purchase price. This document confirms your creditworthiness and income are verified, but the final loan commitment remains contingent upon a professional valuation. If the appraisal comes in low, the loan terms may change or require a larger down payment. It is a critical milestone that signals to sellers you are a serious buyer awaiting only the final property assessment to close the deal.
Pre-Funding Conditional Approval Subject to Property Appraisal Letter
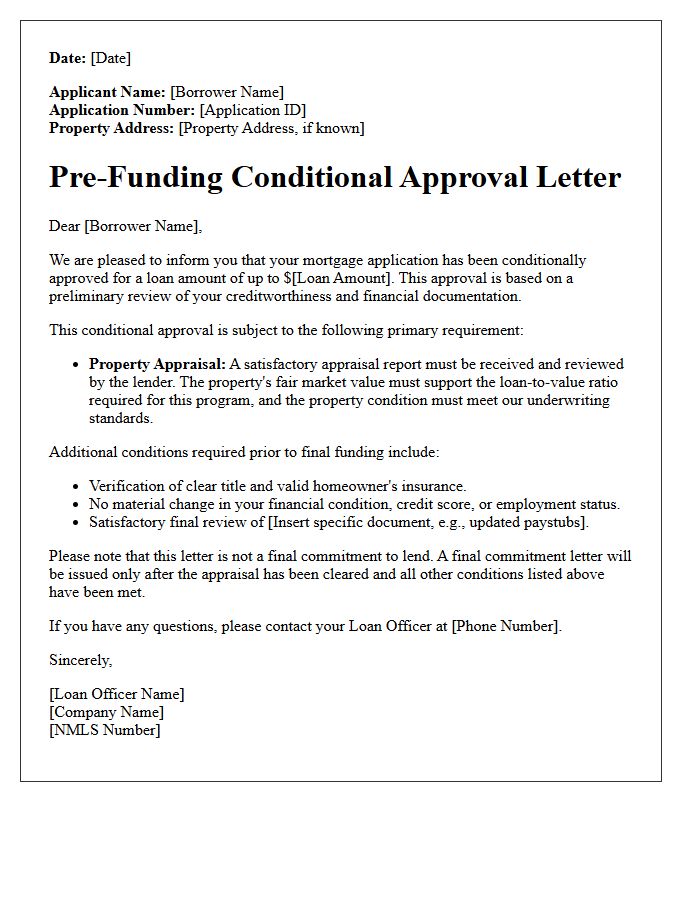
A Pre-Funding Conditional Approval Subject to Property Appraisal Letter confirms a lender is ready to finance your home, provided the property's market value aligns with the loan amount. While your credit and income are verified, the final commitment depends on a professional appraisal report. This document strengthens your offer by showing sellers you are a qualified buyer, though the deal remains contingent on the home passing inspection and valuation standards. It is a critical milestone that bridges the gap between initial pre-approval and the final closing disclosure.
Home Purchase Conditional Approval Pending Satisfactory Appraisal Letter
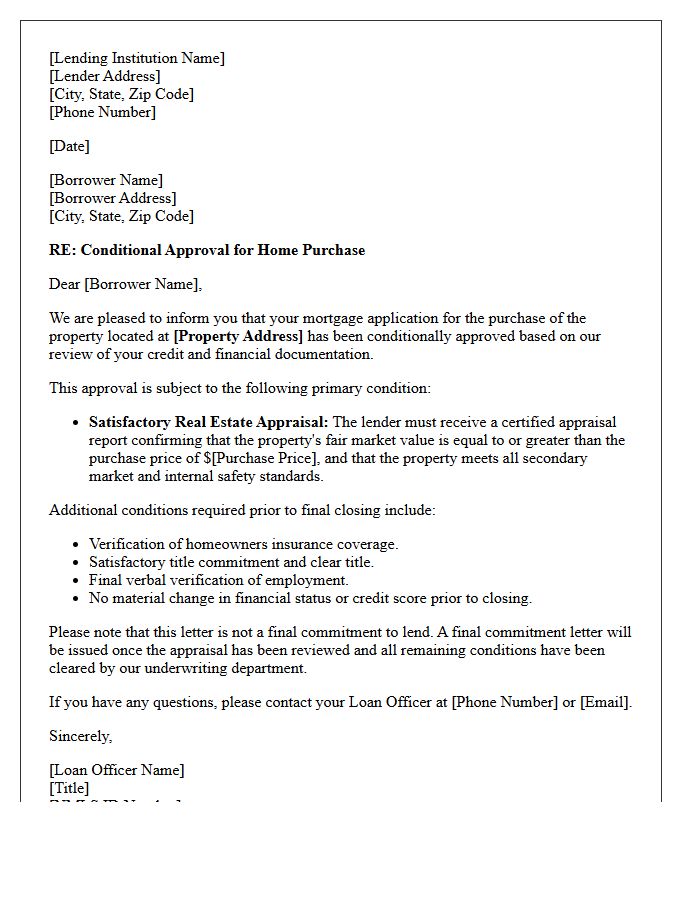
A home purchase conditional approval pending a satisfactory appraisal means the lender has verified your financial profile but requires a professional valuation of the property. The most critical factor is the Appraisal Letter, which must confirm the home's market value matches or exceeds the purchase price. If the valuation comes in low, the lender may reduce the loan amount, requiring you to negotiate the price, pay the difference, or cancel the contract. This letter ensures the property serves as sufficient collateral for the mortgage before final funding is granted.
Conditional Loan Commitment Pending Satisfactory Property Appraisal Letter
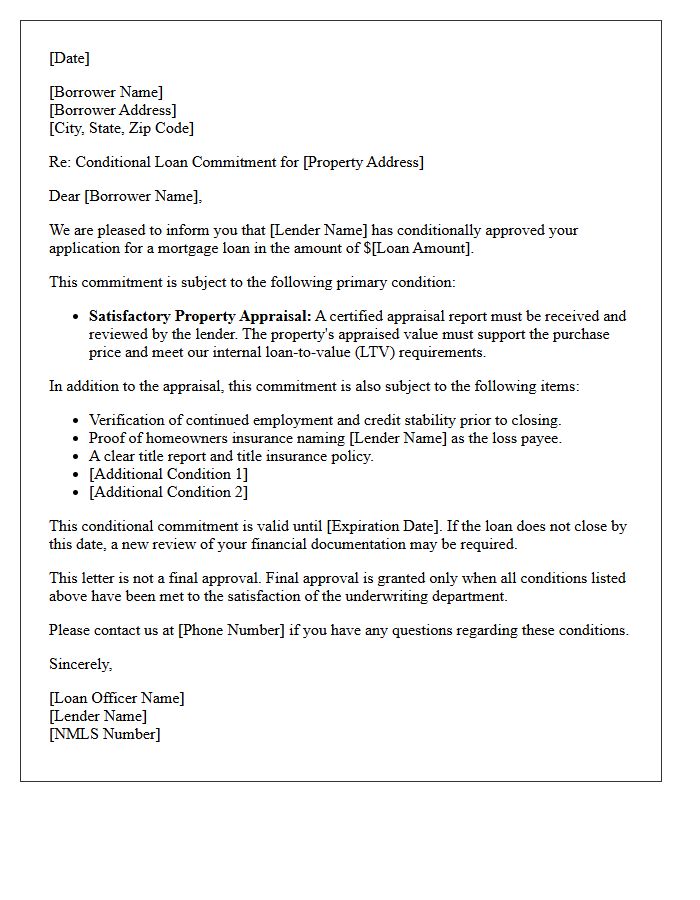
A Conditional Loan Commitment Pending Satisfactory Property Appraisal Letter is a formal notice from a lender indicating your mortgage is approved, provided the home's appraised value meets the purchase price. This document confirms your creditworthiness and income are verified, but final funding remains contingent on the property's worth. If the appraisal comes in low, the loan amount may be reduced, requiring a larger down payment or price renegotiation. It serves as a vital signal to sellers that you are a qualified buyer awaiting only the final valuation results.
Approved Pending Satisfactory Real Estate Appraisal Letter
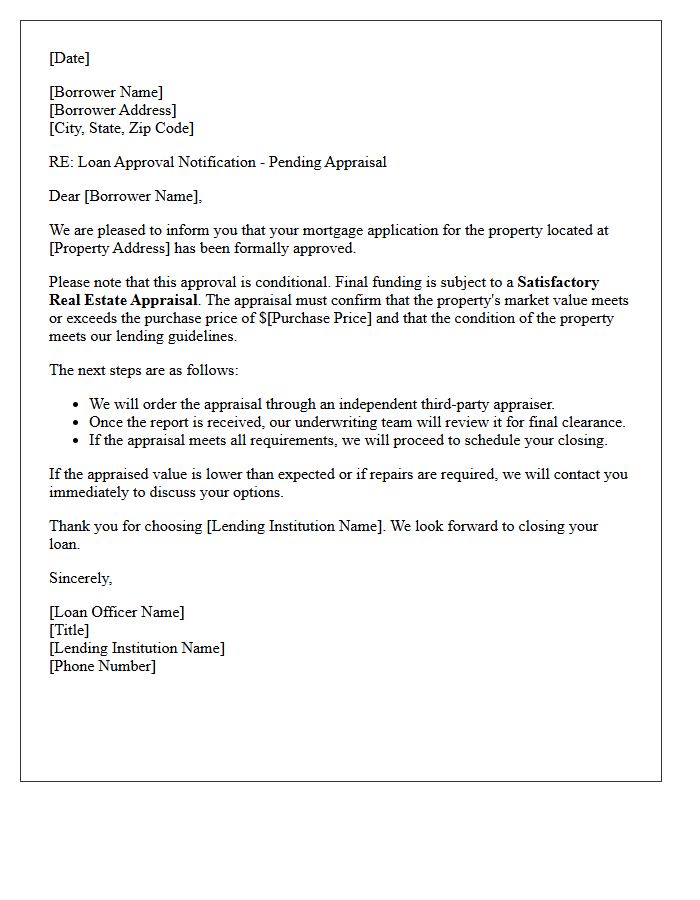
An Approved Pending Satisfactory Real Estate Appraisal Letter is a conditional commitment from a lender. It confirms a borrower is qualified for a mortgage, provided the property's market value meets or exceeds the purchase price. This document is crucial for sellers as it reduces financial risk. However, if the appraisal comes in low, the loan amount may be reduced, requiring the buyer to cover the appraisal gap or renegotiate the deal. It signifies that the final loan approval is solely dependent on a successful property valuation.
What does "Conditional Approval Pending Satisfactory Appraisal" mean?
A conditional approval pending a satisfactory appraisal means your mortgage loan is approved by the underwriter, provided that the home's appraised value meets or exceeds the purchase price and the property condition meets lender standards.
How long does it take to clear an appraisal contingency for final approval?
Once the appraisal report is submitted to the lender, it typically takes 48 to 72 hours for an underwriter to review the document and issue a "clear to close," assuming no repairs or value adjustments are required.
What happens if the appraisal comes in lower than the purchase price?
If the appraisal is lower than expected, the "satisfactory" condition is not met. You may need to cover the valuation gap in cash, negotiate a lower price with the seller, or dispute the appraisal through a Reconsideration of Value (ROV).
Can a lender deny a loan after a conditional approval letter is issued?
Yes, a loan can be denied if the appraisal reveals structural issues, safety hazards, or a valuation significantly lower than the loan amount that the borrower cannot offset with a larger down payment.
What specific property conditions could prevent a satisfactory appraisal?
Issues such as peeling lead-based paint, non-functional HVAC systems, structural foundation cracks, or health and safety violations can prevent a "satisfactory" rating until repairs are completed and re-inspected.

Comments